Week of November 9, 2026

Published every Monday: Get a detailed snapshot of what moved the markets last week—and what to watch this week.

What is the Federal Reserve (Fed) thinking after seeing employment data?

Stocks were lower across the board because of a significant sell-off focused on companies benefiting from the AI buildout. Other areas of the market fared better, with five sectors posting positive returns. The yield on the 10-year Treasury declined to 4.87 percent.

Weekly Quick Hits

Beyond the Headlines

What is the Federal Reserve (Fed) thinking after seeing employment data?

Report Releases

Job creation surged to 165,000 last month, and the data was revised higher for August and September.
Financial Market Data

Stocks were down as investors tried to interpret how election results may affect policy changes.
Looking Ahead

Consumer and producer price inflation data for last month will highlight this week’s economic reports.

BEYOND THE HEADLINES:

What Is the Fed Thinking After Seeing Employment Data?

The market spent last week parsing midterm election results and what they mean for future policy. Most of the debate was focused on AI beneficiaries and whether the data center buildout would slow or face higher costs due to increased regulation. Understandably, economic data took a back seat.

When the Fed chose to leave interest rates unchanged last month, Chair Kevin Warsh said the period between that meeting and the December meeting was “information rich.” Any data that offers insight into inflation or jobs remains important as the market looks forward to the central bank’s December 8–9 meeting. Consensus expectations are that the committee will raise interest rates 25 basis points (bps) after the meeting, though multiple factors will be considered in making that decision.

Job Creation Is Well Above Expectations
Last month’s nonfarm payroll report showed that 165,000 jobs were created, well above consensus expectations for 70,000 new jobs. Further illustrating the strength of the report, the previous two months were revised higher by a combined total of 84,000 jobs. Continued job creation strength was seen in the health care sector, continuing a multiyear trend.

The unemployment rate declined slightly to 4.1 percent. This is a sign that the employment market remains tight, even if it isn’t as robust as it has been in previous years. Wage growth continues to run below inflation, at 3.1 percent year-over-year. If the employment market remains tight, wage growth should improve.

Inflation Data Is Up Next
This week, we’ll see updates on consumer and producer price inflation for last month. Inflation is expected to remain well above the Fed’s 2 percent target, which hasn’t been reached in more than five years, so work remains for the central bank.

The combination of a strong employment market and inflation exceeding 3 percent argues for a rate increase. But have market signals changed in the past few weeks?

How Do Election Results Affect the Fed?
In the past, Warsh has said the Fed should take cues from the market as it deliberates interest rate policy. Leading up to the election and in the days after, the market seemed to be discounting slower growth and a settlement in the Middle East. Oil prices have declined from more than $100 at various points in the fall to less than $90. Some areas have begun to see relief in gasoline prices. At the same time, the 10-year Treasury yield has declined from 5.36 percent to less than 4.9 percent.

The market seems to be sending the message that it expects a slowdown in economic growth. AI infrastructure buildout, which has been a key driver of U.S. economic growth, isn’t expected to slow over the next year. If data center construction draws more scrutiny given the change in governors in critical states such as Texas, however, a slowdown could follow down the road.

If the Fed agrees, it might decide that despite strong employment data, volatility throughout the year gives it cover to leave rates unchanged next month and wait for more data.


“The combination of a strong employment market and inflation exceeding 3 percent argues for a rate increase. But have market signals changed in the past few weeks?”

Report Releases: November 2–6, 2026

ISM Manufacturing Index:
October (Monday)

Manufacturer confidence improved more than expected last month, bringing the index to its highest level in three months. Faster hiring and new order growth supported manufacturers’ views.

  • Expected/prior ISM Manufacturing index: 54.5/54.5
  • Actual ISM Manufacturing index: 55.5

ISM Services Index:
October (Wednesday)

Although service sector confidence dropped last month due in part to slower new order growth, the index remains in healthy expansionary territory.

  • Expected/prior ISM Services index: 54.8/54.9
  • Actual ISM Services index: 54.5

Employment Report:
October (Friday)

Hiring accelerated last month, with the economy adding 165,000 jobs versus expectations for 70,000. The unemployment rate fell to 4.1 percent, signaling continued labor market strength.

  • Expected/prior change in nonfarm payrolls: +70,000/+60,000
  • Actual change in nonfarm payrolls: +165,000

Preliminary University of Michigan Consumer Sentiment Survey:
November (Friday)

Consumer sentiment improved more than expected in November, bringing the index to a three-month high. Improvement was driven by rosier consumer views on current and future economic conditions.

  • Expected/prior month consumer sentiment index: 48.0/48.0
  • Actual consumer sentiment index: 51.0

The Takeaway


  • The employment market rebounded strongly, and data from August and September was revised upward.
  • That strengthens the case for the Fed to increase rates, pending this week’s inflation data.

Financial Market Data

Equity

Equities were lower across the board, in large part because of a late-week selloff that followed a post-election rally. Thursday was the worst day for the Nasdaq Composite (down 3.37 percent) and S&P 500 (down 2.67 percent) since April 2025. The Dow Jones Industrial Average declined 0.94 percent. The equal-weight S&P 500 again outperformed, declining just 1 percent. Crude oil prices fell nearly 13 percent, causing the energy sector to decline 12 percent. The technology sector dropped nearly 7 percent. Five sectors had positive returns, led by consumer discretionary and communication services, which rallied more than 2 percent.
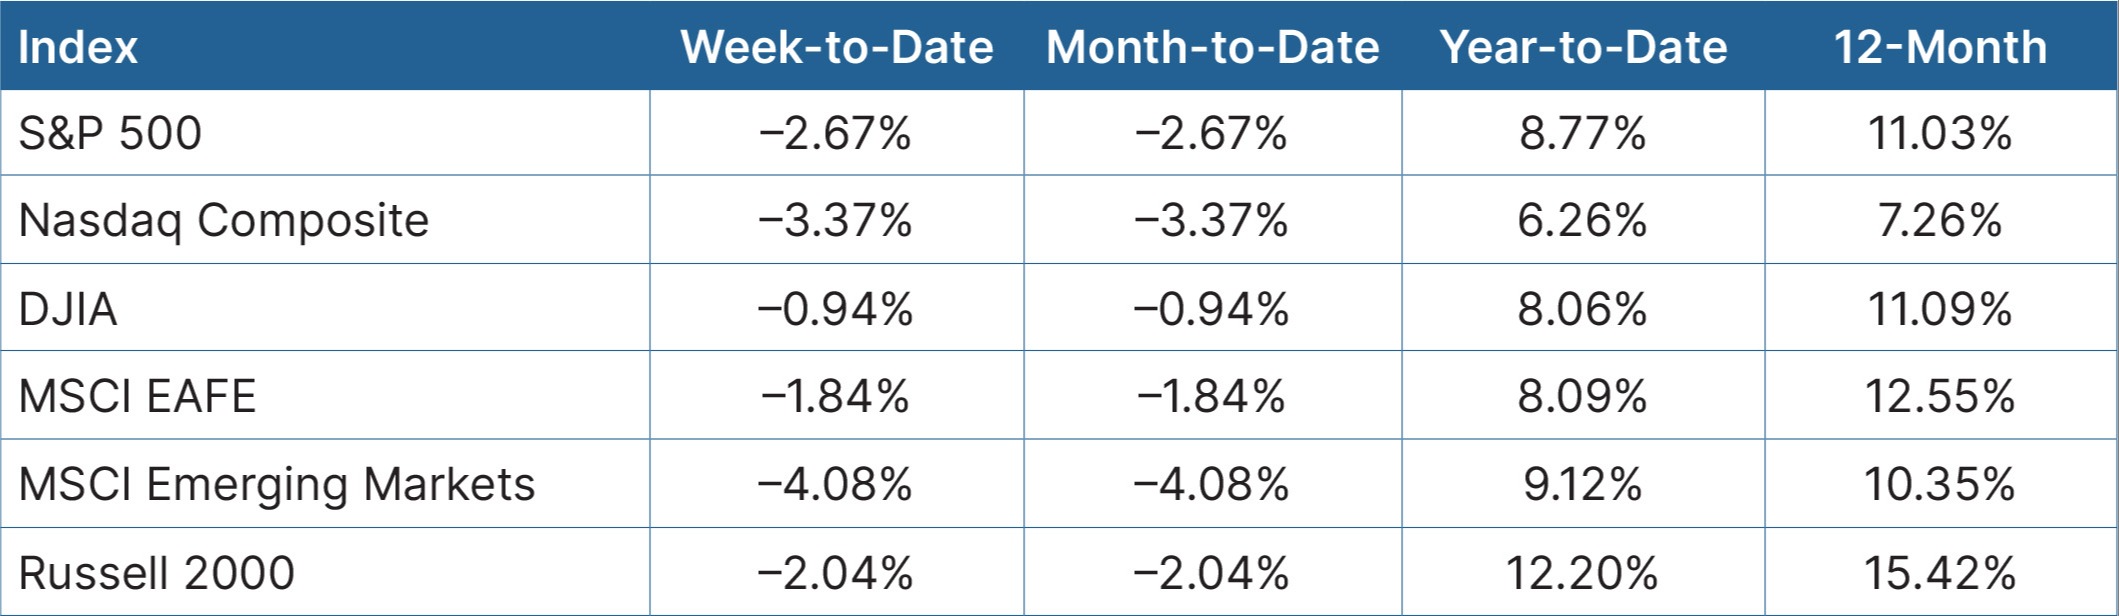
equity graph

Source: Bloomberg, as of November 6, 2026

Fixed Income

The Treasury market once again rallied on a continued flight to quality and concerns about economic growth if the data center buildout were to face increased scrutiny. The 10-year Treasury yield declined 6 bps to 4.87 percent. This led to modest gains in fixed income markets. Core bonds, Treasuries, and mortgages each moved up around 0.5 percent, and the municipal market rose roughly 1 percent.
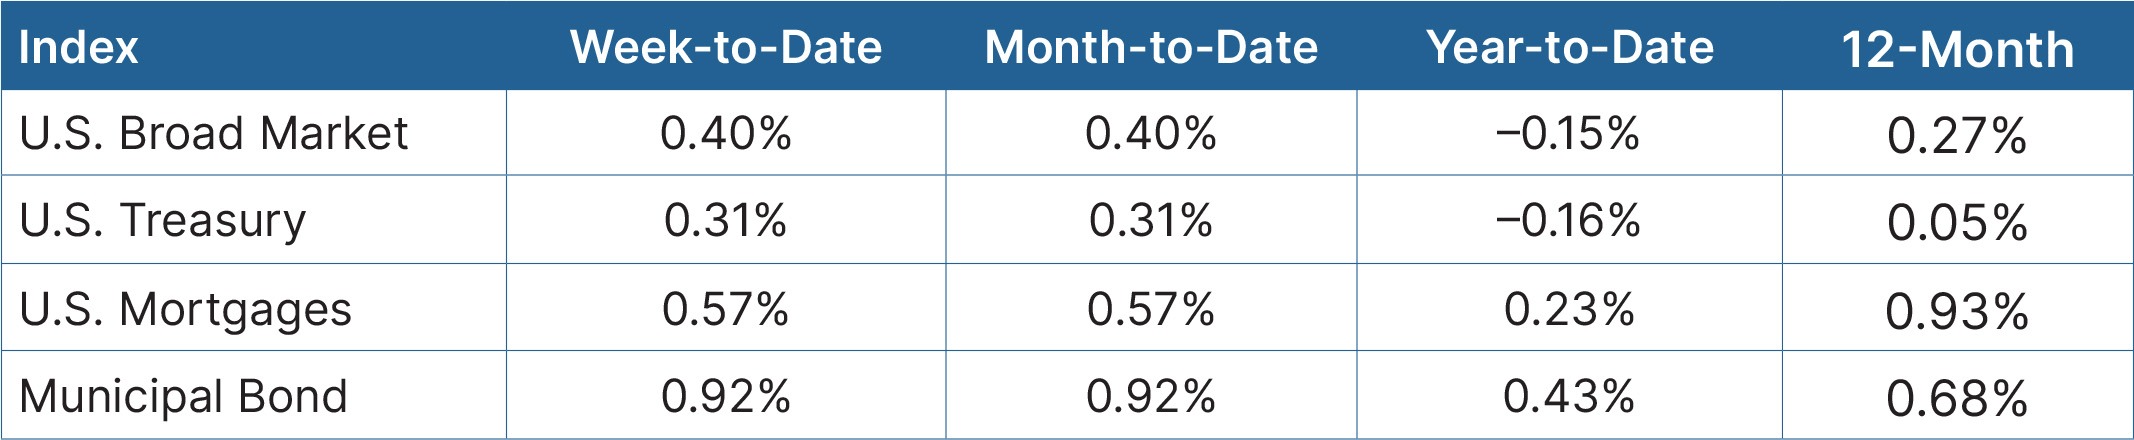
fixed income graph

Source: Bloomberg, as of November 6, 2026

The Takeaway


  • Indices were lower as markets reacted to midterm election results. Rallies on Wednesday and Friday weren’t enough to offset a sell-off on Thursday.
  • It was relatively quiet in the bond market, with Treasury yields declining just a few basis points.

Looking Ahead

Inflation will take center stage this week, with updates to consumer and producer price indices for last month expected.

  • The week kicks off on Tuesday with the Consumer Price Index for October. After accelerating in September, consumer inflation is expected to moderate. Year-over-year figures won’t be reported because last year’s government shutdown limited data collection.
  • On Thursday, we’ll see data on existing home sales for October. The pace is expected to fall more than 3 percent, reflecting headwinds created by rising mortgage rates and high home prices.
  • Finally, on Friday, we’ll see the Producer Price Index for October. Economists expect to see continued producer inflation pressure, with year-over-year increases expected to exceed 6.5 percent.

Disclosure: This material is intended for informational/educational purposes only and should not be construed as investment advice, a solicitation, or a recommendation to buy or sell any security or investment product. Diversification does not assure a profit or protect against loss in declining markets, and diversification cannot guarantee that any objective or goal will be achieved. Please contact your financial professional for more information specific to your situation.

Bonds are subject to availability and market conditions; some have call features that may affect income. Bond prices and yields are inversely related: when the price goes up, the yield goes down, and vice versa. Market risk is a consideration if sold or redeemed prior to maturity.

Certain sections of this commentary contain forward-looking statements that are based on our reasonable expectations, estimates, projections, and assumptions. Forward-looking statements are not guarantees of future performance and involve certain risks and uncertainties, which are difficult to predict. All indices are unmanaged and are not available for direct investment by the public. Past performance is not indicative of future results. The S&P 500 is based on the average performance of the 500 industrial stocks monitored by Standard & Poor’s. The Nasdaq Composite Index measures the performance of all issues listed in the Nasdaq Stock Market, except for rights, warrants, units, and convertible debentures. The Dow Jones Industrial Average is computed by summing the prices of the stocks of 30 large companies and then dividing that total by an adjusted value, one which has been adjusted over the years to account for the effects of stock splits on the prices of the 30 companies. Dividends are reinvested to reflect the actual performance of the underlying securities. The MSCI EAFE Index is a float-adjusted market capitalization index designed to measure developed market equity performance, excluding the U.S. and Canada. The MSCI Emerging Markets Index is a market capitalization-weighted index composed of companies representative of the market structure of 26 emerging market countries in Europe, Latin America, and the Pacific Basin. The Russell 2000® Index measures the performance of the 2,000 smallest companies in the Russell 3000® Index. The Bloomberg US Aggregate Bond Index is an unmanaged market value-weighted performance benchmark for investment-grade fixed-rate debt issues, including government, corporate, asset-backed, and mortgage-backed securities with maturities of at least one year. The U.S. Treasury Index is based on the auctions of U.S. Treasury bills, or on the U.S. Treasury’s daily yield curve. The Bloomberg US Mortgage Backed Securities (MBS) Index is an unmanaged market value-weighted index of 15- and 30-year fixed-rate securities backed by mortgage pools of the Government National Mortgage Association (GNMA), Federal National Mortgage Association (Fannie Mae), and the Federal Home Loan Mortgage Corporation (FHLMC), and balloon mortgages with fixed-rate coupons. The Bloomberg US Municipal Index includes investment-grade, tax-exempt, and fixed-rate bonds with long-term maturities (greater than 2 years) selected from issues larger than $50 million. One basis point is equal to 1/100th of 1 percent, or 0.01 percent.

Authored by the Investment Research team at Commonwealth Financial Network®.

© 2026 Commonwealth Financial Network®

Let’s Talk About Your Financial Future

Whether you’re navigating a volatile market or preparing for the future, we’re here to help.

Schedule a Consultation